Finance · U.S. Economy · Inflation
U.S. GDP Growth Accelerates to 3.4% as PCE Inflation Rises to 3.6%
The economy expanded faster in the third quarter, supported by investment and consumer spending. September’s household data were less comfortable: prices rose sharply, income lagged nominal spending and inflation-adjusted consumption was essentially flat.
By Health Politics Daily News Desk · October 29, 2026 at 11:58 a.m. ET
Verified baseline
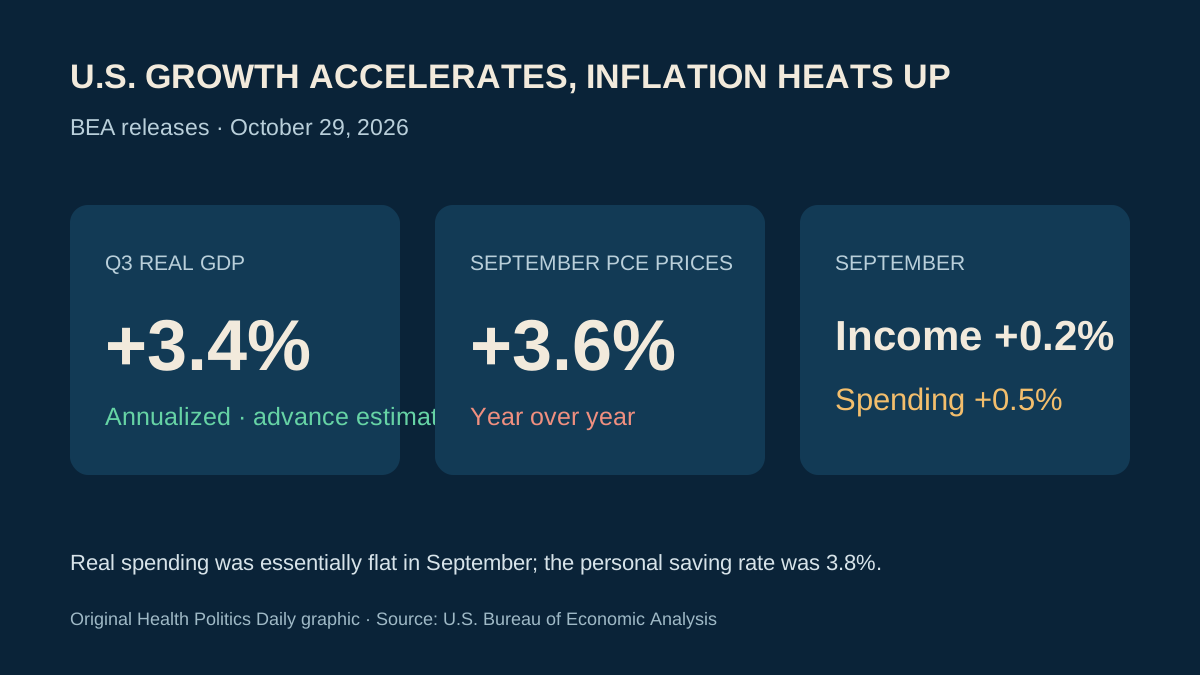
Real gross domestic product increased at a 3.4% annual rate from July through September, up from 2.2% in the second quarter, according to the Bureau of Economic Analysis advance estimate. Investment, consumer spending and government spending contributed; lower exports partly offset the gains, while imports increased.
Separately, the September PCE price index rose 0.5% from August and 3.6% from a year earlier. Core PCE, excluding food and energy, rose 0.3% for the month and 3.1% over 12 months. The Federal Reserve’s longer-run inflation goal is 2%.
Personal income and disposable income each rose 0.2% in September, while current-dollar consumer spending rose 0.5%. After adjusting for price changes, real disposable income fell 0.3% and real consumer spending was essentially unchanged. The personal saving rate was 3.8%.
How strong growth and squeezed households can coexist
GDP measures total inflation-adjusted production across the economy, not whether every household is better off. A 3.4% annualized rate means the quarter-to-quarter change is expressed as though it continued for a full year; it does not mean output rose 3.4% during those three months or that household incomes did.
The quarterly expansion was broad enough to show resilience, with real final sales to private domestic purchasers rising 4.9%. Yet September’s monthly figures suggest momentum cooled entering the fourth quarter: nominal spending increased, but most of that gain reflected higher prices rather than more goods and services.
Practical implications
- Households: faster GDP does not automatically reduce grocery, fuel or housing bills. September real disposable income fell, so budget pressure can persist even in an expanding economy.
- Borrowers: higher PCE inflation can strengthen the case for another Federal Reserve rate increase, but the December decision is not predetermined.
- Workers: economy-wide income rose, but individual wage outcomes vary by industry, hours and location; this release is not a personal pay forecast.
- Businesses: strong investment and demand are supportive, while higher financing and input costs remain risks. The advance GDP estimate will be revised.
Fact, analysis, forecast and opinion
Verified fact: third-quarter GDP grew at a 3.4% annual rate and 12-month PCE inflation reached 3.6% in September. Analysis: the economy remained resilient, but the monthly household figures show that price increases absorbed much of nominal spending growth. Forecast: the data may increase the probability of a December rate rise, but future inflation, employment and financial conditions could change the decision. Opinion: Health Politics Daily takes no political or investment position; readers should judge economic claims using both aggregate growth and household purchasing-power data.
Our report on the Federal Reserve’s divided rate hold explains the policy backdrop. Our coverage of September consumer-price inflation explains why different inflation indexes can produce different headline rates.
Bias Lens: boom, inflation warning or mixed economy?
Verified baseline: GDP accelerated, PCE inflation rose, real September spending was essentially flat and the GDP number is an advance estimate subject to revision.
Left-leaning — The Guardian: emphasizes stronger-than-expected growth alongside persistent inflation and the midterm political backdrop. Center — Associated Press and Reuters: separate the quarterly growth strength from September’s hotter inflation and softer real spending. Right-leaning — Fox Business: leads with inflation remaining above the Fed target while also reporting the stronger GDP reading. The framing differs mainly in which risk receives first emphasis; the BEA figures are the shared baseline.
What remains uncertain
BEA will publish a second GDP estimate on November 25, when more complete data may change the 3.4% figure. The durability of AI-related investment, consumer demand and energy prices is uncertain, as are the Federal Reserve’s December decision and the path of real household income.
Principal sources
- Bureau of Economic Analysis — third-quarter GDP advance estimate
- Bureau of Economic Analysis — September personal income and outlays
- Associated Press — growth drivers and housing context
- Reuters — inflation, markets and rate expectations
No directly relevant official video accompanied the BEA releases. Publisher-authorized Fox Business video analysis exists, but the article omits it because an official data release is clearer than commentary for the verified baseline.
No comments yet.