Finance · Semiconductors · Artificial Intelligence
Arm Revenue Rises 27% as Data-Center Royalties Double
Record revenue and a forecast above Wall Street's average estimate showed continued AI demand. The after-hours decline reflected a different question: whether that growth was strong enough for investors' expectations.
By Health Politics Daily News Desk · November 4, 2026 at 10:00 p.m. ET

Watch in this article
Pumpjack operating at the Kern River Oil Field
A short CC0 field video provides visual context for reporting on oil production and fuel supply.
Thomas Farley / Wikimedia Commons · CC0 1.0 · License and source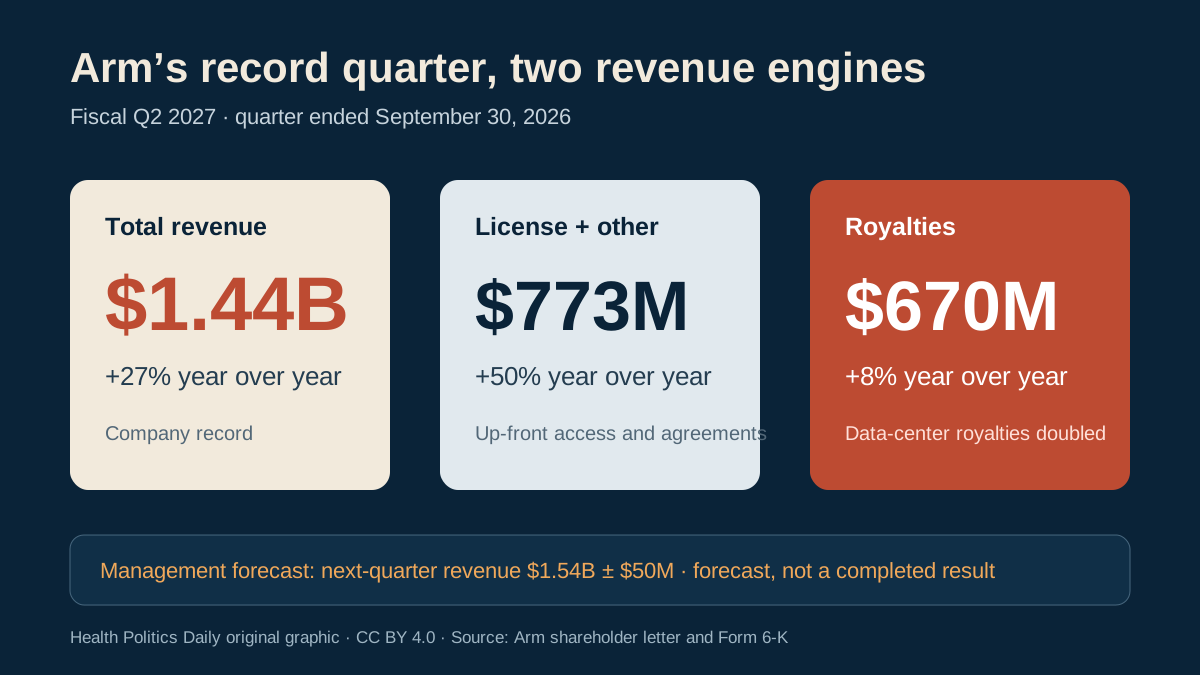
Verified baseline
Arm Holdings reported $1.44 billion in revenue for the quarter ended September 30, up 27% from a year earlier and above the $1.38 billion average analyst estimate compiled by LSEG. Adjusted earnings were 52 cents per American depositary share, compared with a 47-cent estimate.
License and other revenue rose 50% to $773 million, while royalty revenue increased 8% to $670 million. Arm said data-center royalties doubled from the comparable quarter. For its December quarter, management forecast $1.54 billion in revenue, plus or minus $50 million, and adjusted earnings of 56 cents per share, plus or minus four cents.
Arm sells architecture, not finished chips
Arm designs processor architectures and related intellectual property. Customers can pay license fees to use those designs and then pay royalties as products containing Arm technology ship. Arm therefore participates in smartphones, servers, automobiles and connected devices without manufacturing most finished chips itself.
License revenue can be large and uneven because agreements vary in timing and scope. Royalties more directly reflect shipments and prices of products already in the market, although the mix of contracts and reporting lags means they are not a simple count of chips.
Why data centers matter
Smartphones remain a major source of royalties, but AI spending is increasing demand for power-efficient central processors alongside accelerators. Arm says its architecture accounted for more than half of server-chip deployments at major cloud providers in 2025 and expects the share to exceed 60% by the end of 2026.
That deployment-share figure is a company estimate and is not the same as revenue share, unit share across every server, or proof that Arm captures most AI spending. Cloud companies can use Arm-based CPUs while purchasing accelerators, memory and networking components from other suppliers.
Why the shares fell despite a beat
Reuters reported Arm shares fell about 3.5% in extended trading after an initially choppy response. The quarterly result exceeded consensus, and the midpoint of management's next-quarter revenue range was slightly above the $1.53 billion analyst average.
Investors can still sell when a result is better than consensus if expectations embedded in the share price were higher. Reuters also reported that Arm's valuation exceeded 100 times expected earnings before the release. After-hours prices can be volatile and may not predict the next regular session.
Costs, concentration and China
Arm increased research and development spending as it invests in new computing platforms. Higher investment can support future products but reduces near-term margins if revenue does not scale as planned. The company also depends on a relatively small group of major customers and on semiconductor demand cycles.
Arm China contributed about 17% of quarterly revenue. Arm does not control Arm China, which creates governance and collection risks described in company filings. Export controls, trade policy and customer product delays can also affect future licensing and royalties.
Practical implications
- Cloud customers: have more Arm-based server choices, but workload performance, software compatibility and total cost remain system-specific.
- Chipmakers: rising adoption can expand the market for Arm licenses while increasing competition among customers using related architecture.
- Investors: should distinguish reported revenue from guidance, and license growth from recurring royalty growth. This article is not investment advice.
- Consumers: the results do not imply an immediate change in device prices; supply contracts, memory costs, tariffs and manufacturer decisions also matter.
Fact, analysis, forecast and opinion
Verified fact: quarterly revenue rose 27% to $1.44 billion, license revenue rose 50% and reported data-center royalties doubled. Analysis: the mix shows AI-related demand reaching both up-front licenses and shipped products, while smartphone exposure still matters. Forecast: management expects $1.49 billion to $1.59 billion in next-quarter revenue; it is not a completed result. Opinion: Health Politics Daily takes no view on whether Arm shares are fairly valued.
Bias Lens: AI milestone or expectations problem?
Verified baseline: Arm exceeded average quarterly revenue and earnings estimates, guided slightly above the average revenue forecast and reported doubled data-center royalties. Its shares nevertheless declined after hours.
Center — Reuters: emphasizes AI and data-center growth while explaining the share decline through valuation and expectations. Company source — Arm's shareholder letter and Form 6-K: foregrounds records, platform adoption and management's growth case.
No substantial original left-leaning and right-leaning reports focused on this earnings release were available at publication. Forcing political labels onto routine financial coverage would add false symmetry. The meaningful framing difference is between management's promotional account and independent reporting that tests the numbers against expectations.
What remains uncertain
Arm's cloud deployment estimate cannot independently establish its economic share of the server market. License timing can make quarter-to-quarter growth uneven, and management has not guaranteed that doubled data-center royalties will continue at the same rate. Actual revenue will depend on customer launches, product shipments, pricing, export rules and the broader economy.
Principal sources
- Arm — shareholder letter and Form 6-K
- Arm Investor Relations — quarterly materials and webcast
- Reuters — analyst estimates and market reaction
Official Arm earnings webcast and replay is linked rather than embedded so the publisher retains playback and accessibility controls.
No comments yet.